What Credit Score Do You Need to Buy a House in Michigan?
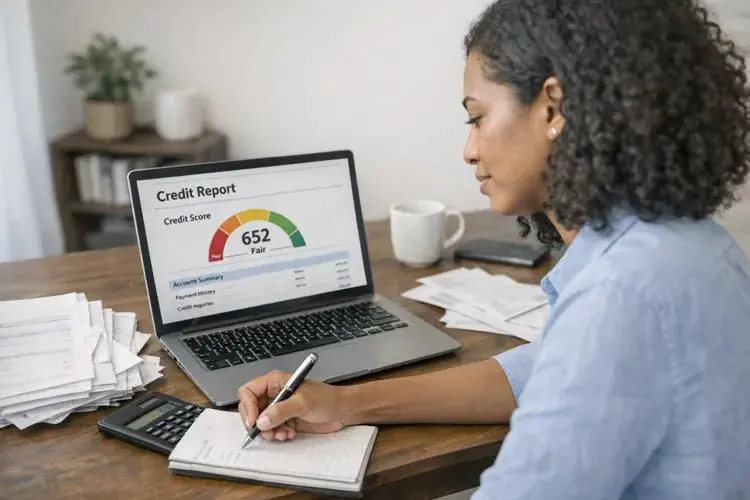
Think Your Credit Isn't Good Enough to Buy a Home? Let's Talk About It!
Let me guess...
You've been dreaming about buying a house, maybe even scrolling Zillow and mentally decorating your future living room. 😂
But there's one little thing holding you back.
Your credit score.
Maybe it's not where you want it to be. Maybe you had a few financial hiccups in the past. Or maybe you haven't even checked it because you're afraid of what you'll find.
Sound familiar?
Here's something I wish more Michigan homebuyers understood:
You do NOT need a perfect credit score to buy a house!
And just because your credit isn't where you'd like it to be today doesn't mean homeownership is out of reach.
So, let's break down what credit score you need to buy a house in Michigan, how different mortgage programs work, and what you can do to start preparing.
1. What Is the Minimum Credit Score to Buy a House in Michigan?
Here's the thing.
There isn't one magical credit score that automatically qualifies everyone for a mortgage.
Different loan programs have different requirements, and individual mortgage lenders may have their own lending standards.
Here's a general overview:
| Mortgage Type | Credit Score Guidelines |
|---|---|
| FHA Loan | 580 for the 3.5% minimum down payment under FHA rules; 500–579 may qualify with at least 10% down |
| Conventional Loan | Varies by loan product and underwriting method; 620 is a common lender benchmark |
| VA Loan | No VA-established minimum credit score; lenders set their own requirements |
| USDA Loan | No universal USDA-guaranteed loan minimum; lenders evaluate credit and repayment history |
Important: These are general guidelines, not guarantees of approval. Mortgage programs, underwriting requirements, and lender standards can change.
Your credit score is only one piece of the mortgage approval puzzle.
2. Can You Buy a House in Michigan With a 580 Credit Score?
Potentially, YES!
FHA loans are often worth exploring for buyers who don't meet the credit requirements for certain conventional mortgages.
Under FHA guidelines, eligible borrowers with credit scores of 580 or higher may qualify for the minimum 3.5% down payment.
But here's what you need to understand.
Just because FHA guidelines allow a certain score doesn't mean every lender will approve it.
Lenders may have additional requirements based on your income, debts, credit history, and overall financial situation.
So if your credit score is around 580, don't automatically assume you can't buy a home.
Talk to a knowledgeable mortgage lender and find out what your options actually look like.
3. What If Your Credit Score Is Below 580?
First of all, don't panic!
A lower credit score doesn't mean you'll never become a homeowner.
FHA rules may allow certain borrowers with scores between 500 and 579 to qualify with at least 10% down, but finding a lender willing to approve that situation can be difficult.
And sometimes, the better option is to spend a few months improving your credit before applying.
That's why I encourage buyers to start preparing 3–6 months BEFORE they're ready to purchase a home.
A little preparation now could make a meaningful difference in your financing options later.
4. Your Credit Score Isn't the Only Thing Mortgage Lenders Look At!
This is something I really want first-time homebuyers to understand.
Your credit score matters, but it isn't the whole story!
Mortgage lenders also consider things like:
-
Your income and employment history
-
Your monthly debt payments
-
Your debt-to-income ratio
-
Your savings and available funds
-
Your payment history
-
The type of mortgage you're applying for
For example, someone with a higher credit score but significant monthly debt may have a different borrowing situation than someone with a slightly lower score and very little debt.
That's why two buyers with similar credit scores may qualify for very different mortgage amounts or loan terms.
5. How Can You Improve Your Credit Before Buying a House?
Okayyyy, let's talk about what you CAN control! 🙌
If you're hoping to buy a home in Michigan within the next several months, here are some practical ways to start preparing.
Pay Your Bills on Time
Payment history is a major factor in many credit scoring models.
Set reminders or automatic payments when possible to help avoid missed payments.
Work on Lowering Credit Card Balances
Your credit utilization, or how much of your available revolving credit you're using, can affect your score.
Paying down balances may help improve your credit profile.
Avoid Opening Unnecessary New Credit Accounts
Planning to buy a house soon?
This probably isn't the best time to finance a new vehicle, open several store credit cards, or take on additional debt without discussing it with your lender.
New accounts and payments can affect your mortgage qualification.
Check Your Credit Reports for Errors
You can request free credit reports through AnnualCreditReport.com.
Look for accounts you don't recognize, incorrect balances, or inaccurate payment information.
If you find errors, you have the right to dispute them.
Don't Automatically Close Old Credit Cards
Closing an account can sometimes affect your available credit and credit history.
Before making major changes, ask your lender how they might affect your mortgage application.
And remember: Credit improvement takes time. There's no guaranteed overnight fix.
6. Will Checking My Credit Hurt My Score?
This is another question I hear all the time!
Checking your own credit is considered a soft inquiry, which does not hurt your credit score.
When a mortgage lender checks your credit as part of an application, that may create a hard inquiry.
However, many credit scoring models treat multiple mortgage inquiries made within a designated shopping period as a single inquiry for scoring purposes.
So don't be afraid to learn where you stand!
Knowing your starting point is one of the best ways to create a realistic plan.
7. Does a Higher Credit Score Help You Get a Better Mortgage?
It certainly can!
A stronger credit profile may help you qualify for more mortgage options and potentially better interest rates or loan terms.
And even a relatively small difference in your mortgage interest rate can add up over the life of a loan.
But don't get so focused on reaching a particular number that you forget the bigger picture.
The goal isn't simply to have a great credit score.
The goal is to become financially prepared to comfortably own a home.
Frequently Asked Questions About Credit Scores and Buying a House
Can I buy a house with bad credit in Michigan?
Possibly! Your options depend on your credit history, income, debts, available funds, mortgage program, and lender requirements.
Do first-time homebuyers need a higher credit score?
Not necessarily. First-time homebuyers may qualify for several different mortgage programs, each with its own requirements.
Does getting preapproved hurt your credit?
A mortgage preapproval may involve a hard credit inquiry. Ask your lender what type of credit check they'll perform.
How long does it take to improve your credit score?
It depends on your situation. Some changes may appear after updated balances are reported, while more significant credit issues may take longer to address.
Think Your Credit Is Holding You Back? Let's Make a Plan! ❤️
If you've been putting off buying a house because you're worried about your credit, please don't assume you're out of options before you've even explored them.
I offer FREE one-on-one homebuyer seminars where we walk through the ENTIRE homebuying process together!
We'll talk about preparing your finances, connecting with a mortgage lender, down payment assistance, house hunting, making offers, inspections, closing costs, and everything in between.
And if you're not quite ready to buy?
That's completely okay!
We'll focus on helping you understand the process and what steps you can take next.
No pressure. No obligation. No strings attached.
Whether you're looking to buy in Grand Blanc, Flushing, Davison, Flint, Clio, Swartz Creek, or another Mid-Michigan community, I'd love to help you get started.
You don't have to have everything figured out to take the first step. 🏡♡
Brittany Buchholz | Dream Homes by Brittany B | REAL Brokerage
📱 810-347-1498
Where Dreams Meet Addresses! ♡
Categories
Recent Posts